
Compliments of
 Alan Van Zee
President | NMLS #: 297154
Hawaii Mortgage Company, Inc.
Company NMLS #: 232582
Alan Van Zee is one of the top producing Mortgage Originators in the state, originating over $2,000,000,000 to date. He has written and published this weekly newsletter for the past 19 years. It is the most widely read mortgage, real estate, and finance publication in Hawaii.
Hawaii Mortgage Company, now in our 28th year of providing mortgages to the people of Hawaii, is proud to have a complaint-free history. We make sure our clients are happy!
News and Insight
For the Weekend of August 29th, 2026
Hawaii’s Most Read Mortgage, Real Estate, and Finance Publication for 18 Years
Volume 19 – Issue 1
Mortgage Inquiry Triggers Estate Planning & A Lesson on Blended Rates
Most families in Hawaii can’t afford the high cost of living. Many are looking towards multi-generational options to beat the expense but also keep family together. I got a call this week from a long-time client with a simple plan: Access the equity in his home to expand his living area to accommodate his daughter and her young son. This plan not only allows the parents’ home to be expanded and increase its value but also allows them to aid in much needed childcare helping their daughter while at work. I talked with Stan on the phone for a while to understand exactly what he wanted. I’m not a simple order taker, as I addressed two major points I needed him to consider.
Issue #1 – The Great Existing Mortgage Rate:
I helped Stan refinance his home in 2021 and got him a 2.750% fixed rate. He was adamant that he didn’t want to give up that loan in order to make this expansion happen. In fact, Stan had shopped around and found that it was harder than he thought to get a bank to give him the necessary funds to complete the project.
Stan is fortunate to have a relatively small 1st mortgage. Unfortunately, the cost to expand his home is significantly higher than anticipated. The way underwriters qualify borrowers for 2nd lien loans (HELOC’s and Fixed-Rate seconds) is different than how regular 1st lien mortgages are done. There was an issue with sufficient income to qualify.
The more important aspect I shared with Stan was the concept of “blended rates”. When you take on a huge 2nd mortgage to protect the 1st mortgage, you need to calculate the ENTIRE combined mortgage. That’s an important calculation. In Stan’s situation, a new 1st mortgage, even at a much higher rate than his current one, will still have an interest rate and payment smaller than a combined existing 1st and new 2nd.
Issue #2 – What Happens When the Parents Pass Away?
One of the reasons Stan wanted to have two separate mortgages is so he could continue to pay his mortgage while his daughter paid the mortgage on the home expansion. That seemed weird to me, so I asked Stan if there were any other kids. It turns out Stan and his wife have 3 kids. I asked what the plan was when they pass, and the response was “I guess we should figure that out.” Damn right! They are about to add one child to title for this expansion project. It has been my experience over the past almost 3-decades that with siblings, one will always want to reside in the family home, while the other(s) want their equity position. If the one sibling currently living in the home - in this case the daughter wants to keep the home, she would need to refinance to access the equity owed to the other siblings. But what happens if that sibling living in the home can’t qualify to refinance to access the equity? I have seen it first-hand get ugly. I have witnessed court-ordered sales for the other siblings to get what’s rightfully theirs.
The one thing I can almost guaranty - all your kids will not want to live together with their spouses and kids. I have only seen that once, and it was 3 siblings all in their 70’s with no kids or spouses.
Reflect on the two topics above.
First, if you have a great rate on your 1st mortgage and need to access the equity in your home, it may be a smarter idea to refinance into a new 1st mortgage, instead of getting a higher rate 2nd mortgage. It all depends on the numbers. If you want, give me a call, and I’d be happy to do the math for you.
Second, before you decide to make your home a multi-generational property with one of your children, have a plan in place – preferably a trust, to be the road map of how that property is to be treated upon your death.
Thoughts from a Reluctant Traveler
I had the proud but sad task of dropping my son off to college on the mainland last week. We headed up to the mainland a few days early so we could have a last father-son road trip before he started school.
While on the mainland, we had the opportunity to visit some local parks in three different areas. I should add to the story that we were in Texas the entire time. My son was the first one to realize this fact: He asked, “Dad, why are all the public restrooms nice and clean, when the ones back home in the parks are destroyed and disgustingly dirty?” My question as a lifelong resident of Hawaii is “Why do so many local residents hate our public restrooms?” If you haven’t been to a local park restroom in Hawaii recently, consider yourself lucky. Broken sinks, broken toilets – not just out of order, actually physically destroyed. Either damaged by someone using an object to crack the porcelain, or an attempt was made to rip the fixture off of the wall. I jokingly use the word hate, but a large group of people are taking their anger out on public restrooms. It’s been going on since I was a kid, it is still a major problem, and for the life of me, I have no clue why. I haven’t seen that phenomenon on the mainland.
The other observation I had on this trip was upon my departure and return to the “Dan” – the Daniel K. Inouye Honolulu International Airport. Everyone at airports these days are stressed and on edge. The airport administration deems it very important that they repeat the same messages over the PA system over and over again. What I can’t figure out is why the announcements – if so important, are voiced in both English and the Hawaiian languages. I am all for a cultural awakening, but let’s get honest, how many people at any given moment at HNL can actually understand that what’s being said when announced in Hawaiian?? There is a time and a place. But I don’t think airports need to double as vanity educational hubs. If the announcements are that important, they should be in the languages most travelers to and from Hawaii use. If the goal is to expand travelers’ knowledge of the Hawaiian language, which I think would be a good idea, then come up with separate announcements teaching travelers Hawaiian words and phrases. That would be more appropriate.
Newsletter Starts its 19th Year!
In 2008 in the midst the financial crash, I decided I was tired of people in my industry giving bad advice to consumers, and that consumers in general needed to be better educated about mortgages, real estate, and finance. My plan was to write a newsletter. I wasn’t sure how often I would write it, because I was concerned, I would run out of topics. I was also concerned if it would be well received – after all, we all get enough junk in our email inbox.
18 years and over 750 newsletters later, with a distribution of almost 20,000 subscribers, my weekly newsletter has become my weekly joy to present to you. The newsletter has expanded from mortgage specific topics like Fixed-Rate loans vs. Adjustable Rate (ARM) products, to financial insight such as the lost opportunity of waiting to purchase by continuing to rent. I’ve also not been shy to comment when government fails us or other general issues of interest (like today’s comments above about coming home to Hawaii after a trip to the mainland).
I’ve always said to anyone that subscribes…I don’t expect you to read every issue, but you may wish to give it a quick scan to make sure you’re not missing anything. To the hundreds of you that over the years reached out personally to comment, complain, or thank me, the fact you took the time to respond tells me I connected with you in some way. That connection is the reason I’ve continued all these years.
If there’s a question or topic you wish for me to write about, let me know. My goal is to hit 25 years…
And now the week’s economic news…….
Steady Inflation
Mortgage markets were relatively quiet this week, as the major economic events caused little reaction. A highly anticipated speech from Fed Chair Warsh avoided new forward guidance on monetary policy, the latest inflation data matched expectations, and mortgage rates finished slightly lower.
Over the past few months, long-term bond yields, including the yields that influence U.S. mortgage rates, have been moving higher around the world. For example, Germany's bond yields recently reached their highest levels since 2011, while Japan's climbed to their highest level in 30 years. There are several reasons behind the broader rise. First, inflation remains elevated in many countries, and higher oil prices since the start of the conflict in the Middle East have added inflationary pressure. When investors expect inflation to remain higher, they typically want a larger return on their investments to protect their purchasing power. Second, investors are keeping a close eye on government spending. Governments around the world are running large deficits and need to issue more debt to fund them. With more bonds competing for money from investors, yields generally need to rise to attract buyers. Another factor is the huge amount of money being invested in artificial intelligence. Technology companies are spending heavily to build AI infrastructure, increasing their need for capital. That means they are also willing to offer higher returns on corporate bonds to attract investors. Put it all together, and there's a lot of demand for investor capital at the same time that the supply of bonds is increasing.
Speaking from the Jackson Hole economic summit on Friday, Fed Chair Warsh expressed concern about elevated inflation levels while avoiding forward guidance on changing the federal funds rate. He noted that recent data did not tell him that underlying inflation trends "have meaningfully improved." While suggesting in general terms that tightening may be necessary if inflation does not come down "at sufficient speed." He did not elaborate on the specific economic signals which would determine policy changes.
Fed officials carefully monitor inflation, and the PCE price index is their favored indicator. As expected, core PCE in July was 3.3% higher than a year ago, the same annual rate as June. Progress toward the 2.0% target of the Fed has been challenging, and this level has not been seen since February 2021.
Next Week
Looking ahead, attention will remain fixed on the conflict in the Middle East. Investors also will monitor comments from Fed officials about future monetary policy. For economic data, The ISM national manufacturing sector index will be released on Tuesday and the services sector index on Thursday. JOLTS also will come out on Tuesday. The key Employment report will be released on Friday, and these figures on the number of jobs, the unemployment rate, and wage inflation are always closely watched.
Until next week….

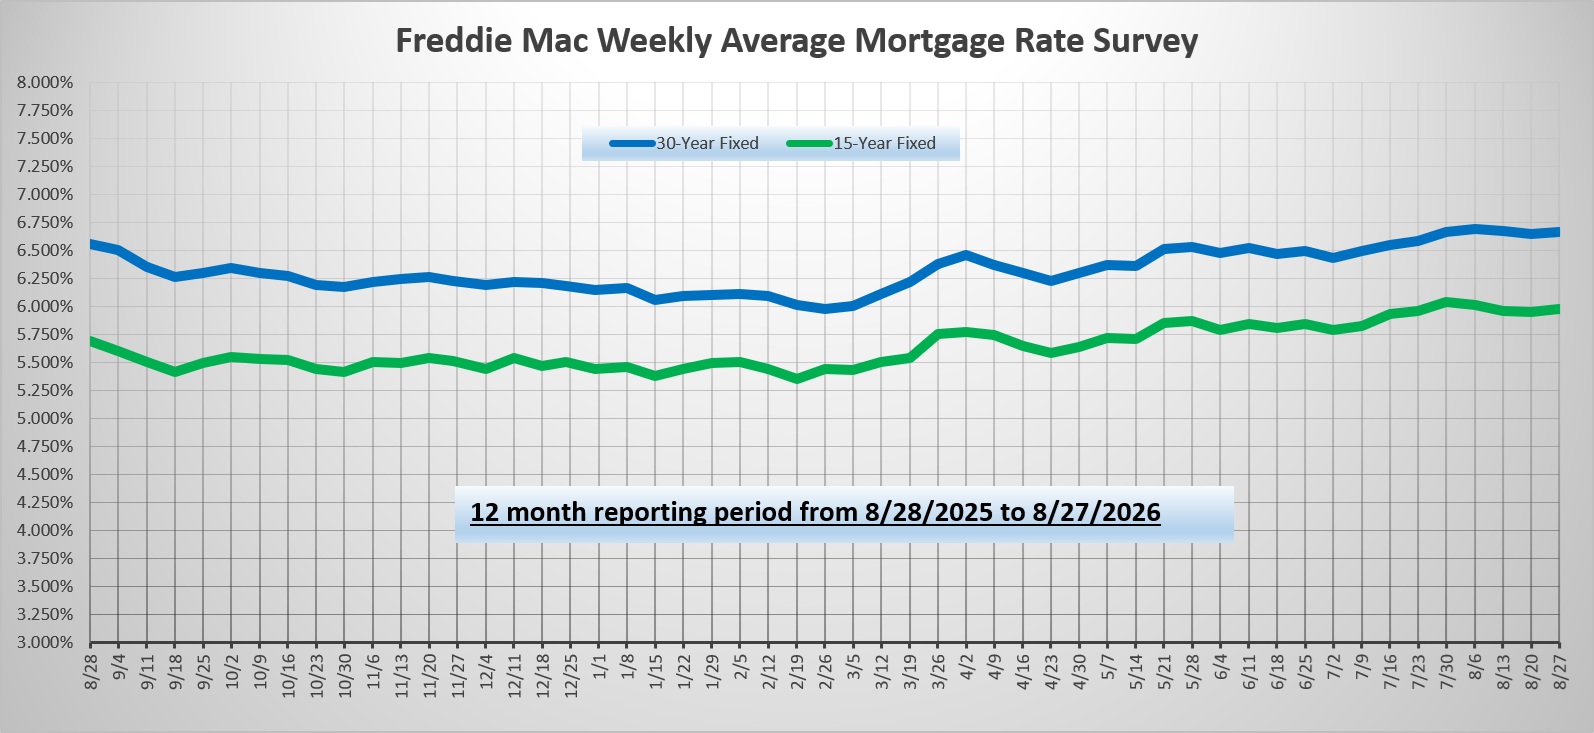
*** Please note that Freddie Mac publishes their weekly rate report on Wednesday mornings from data received Monday and Tuesday.
The graph above is intended to shown rate trends, and not “today’s current rate”. ***
Reviews From Our Past Clients
With every client, we promise to provide you with a comprehensive analysis of your mortgage needs, the best service possible, and the best rates we can find. We make it our mission to have every transaction close with our clients happy with the service we provided. Browse through the hundreds of reviews we’ve received from our clients posted on both Google and Zillow.com, and read what they thought of their experience using Hawaii Mortgage Company.
Google Link:
Hawaii Mortgage Company Review on Google.com
Zillow.com Link:
Hawaii Mortgage Company Reviews on Zillow.com
Our Rate Quote System is Available to You
Our automated rate quoting system is live. Now you can check rates and try different scenarios 24-hours a day. Remember, it’s just a computer. For non-standard rate quotes, such as construction, vacant land, and other specialty programs, you’ll still need to give a call.
Here’s the link: https://www.hawaiimortgage.net/todays-rates/

Do you think all lenders are the same?
There is a difference when you use Hawaii Mortgage Company for your financing. Here’s a short video telling you why:

Broker vs. Banker?
Click the link below to get a quick lesson on why working with a Mortgage Broker will benefit you on your next transaction.


