
Compliments of
 Alan Van Zee
President | NMLS #: 297154
Hawaii Mortgage Company, Inc.
Company NMLS #: 232582
Alan Van Zee is one of the top producing Mortgage Originators in the state, originating over $2,000,000,000 to date. He has written and published this weekly newsletter for the past 19 years. It is the most widely read mortgage, real estate, and finance publication in Hawaii.
Hawaii Mortgage Company, now in our 28th year of providing mortgages to the people of Hawaii, is proud to have a complaint-free history. We make sure our clients are happy!
News and Insight
For the Weekend of September 19th, 2026
Hawaii’s Most Read Mortgage, Real Estate, and Finance Publication for 18 Years
Volume 19 – Issue 4
Don’t Get on the Wrong Side of your HOA
Social media is a buzz with horror stories about Homeowners Associations across the country doing all kinds of terrible things to the people that live in their projects. Today let’s take a dive into the powers your HOA has over your peaceful enjoyment of your home.
The image most people have of their Homeowners Association (HOA) is a group of Karens that volunteer on the board so their complaints can be heard. I have served on HOA boards and can confirm that in almost every situation there was something that each board member was unhappy with that motivated them to get elected. Pet peeves such as trash, noisy neighbors, landscaping, are always huge motivating factors. But the chief Karen concern? Rising monthly HOA dues.
Condo associations are under tremendous strain from owners to keep their monthly HOA fees as low as possible. Rarely is there waste or duplication of services at a project, so the pressure to keep maintenance fees low is really a cry to avoid or defer repairs. This almost always ends bad where the HOA will eventually pay more to fix things later than what it would have cost if the project were properly maintained.
Here in Hawaii, we must also realize that most condo projects were built between 1970 and 2000. With some projects almost 60 years old, many of the internal infrastructure components such as sewer lines and water lines may require complete replacement. I’ve never seen a line item in any reserve study from 10 years ago that listed replacement of sewer lines as a component they should be saving up to replace. Most HOA boards have the power to issue special assessments to all owners to make repairs to the project without the vote of the owners themselves. With rising cost to maintain and repair aging condo projects, associations are feeling the economic pinch. I’ve seen more notices of projects issuing assessments in the last 24 months than I have seen in 20 years.
The associations are also feeling the pinch from delinquent owners for monthly HOA dues. With tough economic times, we’re seeing higher delinquency rates in projects. If a project has too many delinquencies, owners are unable to obtain bank financing. Why should the banks care about other owners if you have good credit and income and are not a risk? When a homeowner fails to make their payment, that’s less money collected by the association that month. Multiply that by 5 or 6 or 10, and that could mean a $5,000 to $15,000 shortfall for the HOA each month.
With all the storm damage and loss of work for many here in Hawaii, there will be many that can’t make ends meet. Everyone knows that if you don’t pay your mortgage, you’ll damage your credit. But HOA’s don’t report to the credit agencies, so too many people think that skipping the monthly HOA bill is the lessor of two evils. It may be the lessor of the two evils, but the damage and path you’ve put yourself on could lead to disaster.
Did you know that your HOA has the right to file a foreclosure action against you if you become delinquent in owing them fees? Yes, you could lose your home if you owe your HOA and are seriously delinquent. An Arizona man lost his job and fell behind on his HOA dues. The amount in arears was $977, but it was 1½ years delinquent. The association turned the matter over to an attorney to collect. That added an additional $10,000 to his bill with the association. The homeowner couldn’t understand how a $977 bill ballooned into one over $10,000. The home, which was owned free & clear with no mortgage, was sold at a foreclosure auction for under $9,000. The home was valued at $475,000. The homeowner is now pleading for help to get his home back.
And it’s not just for past-due monthly fees that can jeopardize your homeownership…
It used to be that if a homeowner in a project violated the house rules, they got fined. In almost all cases, the fine was paid and the issue was done. But it seems that the divide we see politically has crept its way into another crease of America’s fabric. We no longer seem to be able to be civil with each other and just live peacefully. There’s no better example than in projects where homeowners are being fined because they have chosen to display an American flag – a rule violation in some projects, unless it’s 4th of July. But any infraction today seems to incur an immediate fine. But here is where things start getting serious. What if the homeowner disregards the fine and continues the activity and the fines keep piling up? Just like past due monthly HOA fees, it you have lingering fines that become seriously delinquent, your HOA could initiate a foreclose action.
As they say, you can try and fight city hall… Actually, only old people use that expression. But the sentiment rings true. You can try and fight your HOA, but the cost and time may not make it worth the trouble.
That is why you need to research a condo project before buying into that project. Read the past association board minutes. If you already own a unit in a project, attend your board meetings. If not, you’re letting the Karens run the show. And that’s not good for anyone.
A Pro Got Fooled – Take Some Notes
I consider myself a technology geek. I’ve built computers from parts and know my way around a network. But even a seasoned geek like me got fooled – and luckily it could have been much worse.
I was having an issue with my home network. We have an Orbi mesh network, something we got at Costco a couple of years ago. If you don’t have a mesh network setup for your home yet – get one. But that’s not my story.
When I was having problems logging into my home network, I decided to contact Orbi - which is owned by Netgear (one of the largest computer accessory manufacturers in the world). I looked online for Orbi and saw the site to log in from the web. Unfortunately, I didn’t look close enough and the web address was not an official Orbi or Netgear site, it was for a 3rd party company. I didn’t try and log in, instead I called what I thought was Orbi’s technical support department.
The technician listened to my issues and suggested we do a screen sharing session. I do them all the time with my clients, so I didn’t think anything was odd. I was able to see everything the technician did. He initiated some commands on my computer that showed I had somehow gotten a virus. I found this weird because the issue wasn’t with my computer, it was with my Orbi network.
His solution was a $289 fee for their technicians to scan my entire network and would guarantee the removal of what he found, plus anything else that’s not supposed to be there. For $100 more, I could get 3 years of protection!
I told him I would need to think about it and call them back. We ended the session with nothing more done. I’m glad a took a breather and didn’t proceed. It was a scam. Luckily, the scam was just a scam, and wasn’t malicious. That technician could have installed viruses or a program to capture my keyboard typing. The commands he ran on my computer were bogus and there were no viruses. It was all an act to sell me a service I didn’t need. I confirmed this by contacting a local IT firm that ran a real diagnosis to make sure nothing foreign was installed without my knowing.
I later went back and looked at the web search results I saw when I originally tried to contact Orbi. There it was. The link I clicked didn’t have the correct name. It didn’t end with “.com” but it ended with “.shop”. The clear sign of a bogus site.
For me, the mistake cost a little bit of money and some time, but it could have been significantly worse. I have no idea what could have happened if I let them install software on my computer and pay them to do it! If I got played, it would be easy for anyone to get scammed. That’s why I wanted to share with you that these scammers are so good, even tech people who should know better are vulnerable.
If you need to contact a large major company and you do a search online for that company’s phone number or website address, be very careful make sure the link you click is for that actual company and not a bad actor taking advantage of you. If you have official documentation, look for a phone number or web address there first. It is important to realize that the internet and search engines don’t police the listings you’ll find online.
And now the week’s economic news…….
Fed Hike
Mortgage rates had another bumpy week as oil prices fluctuated, and investors digested the latest news from the Federal Reserve and the economy. Despite a Fed rate hike and stronger than expected consumer spending, mortgage rates finished the week almost where they started, remaining near their highest levels in more than a year.
Mortgage markets have been especially volatile lately, and much of this week's action centered around the highly anticipated Fed meeting on Wednesday. In a unanimous vote, all twelve Fed officials agreed to raise the federal funds rate for the first time since July 2023 by 25 basis points. The meeting statement was similar to the prior one. The Fed's outlook for future rate hikes was less clear. The projections from officials varied widely, although the most likely scenario pointed to one more 0.25% increase. Comments from Chair Warsh following the meeting increased investor confidence that the Fed remains focused on bringing down stubbornly high inflation.
So, why didn't mortgage rates jump after the rate hike? The key is that the federal funds rate and mortgage rates are two different things. The federal funds rate is a very short-term rate used for overnight lending between banks. Mortgage rates, on the other hand, are longer-term rates influenced by many factors, including the outlook for inflation and the overall economy. Because the rate hike this week was widely anticipated by investors, it had already been priced into financial markets. Generally, only unexpected events such as an economic report which significantly deviates from the consensus forecast or an unforeseen Fed policy change causes a major move in mortgage rates.
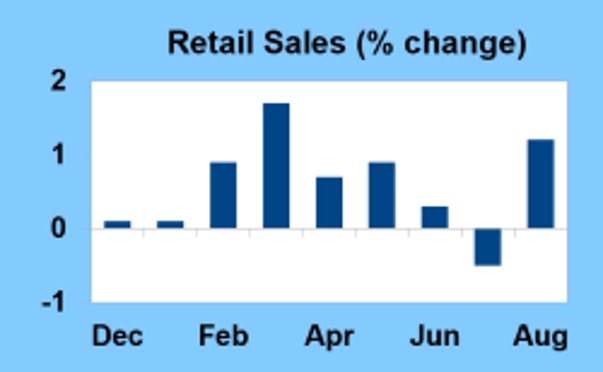 Following an unexpected decline of 0.6% in July, retail sales surged 1.2% in August, exceeding the consensus forecast and the strongest monthly reading since March. Consumer spending was a solid 6% higher than a year ago, despite higher gas prices and economic uncertainty. Much of that spending continues to come from higher-income households, supported by continued strength in the stock market.
Bottom Line: Expect more volatility in mortgage rates as investors weigh comments from Fed officials, upcoming economic reports, and changing oil prices tied to the conflict in the Middle East. For homebuyers and homeowners watching rates, inflation data will be especially important in the weeks ahead.
Next Week
Looking ahead, attention will remain fixed on the conflict in the Middle East and oil prices. Investors also will monitor comments from Fed officials about future monetary policy. It will be a very light week for economic reports. New Home Sales will be released on Thursday and Durable Orders on Friday.
Until next week….

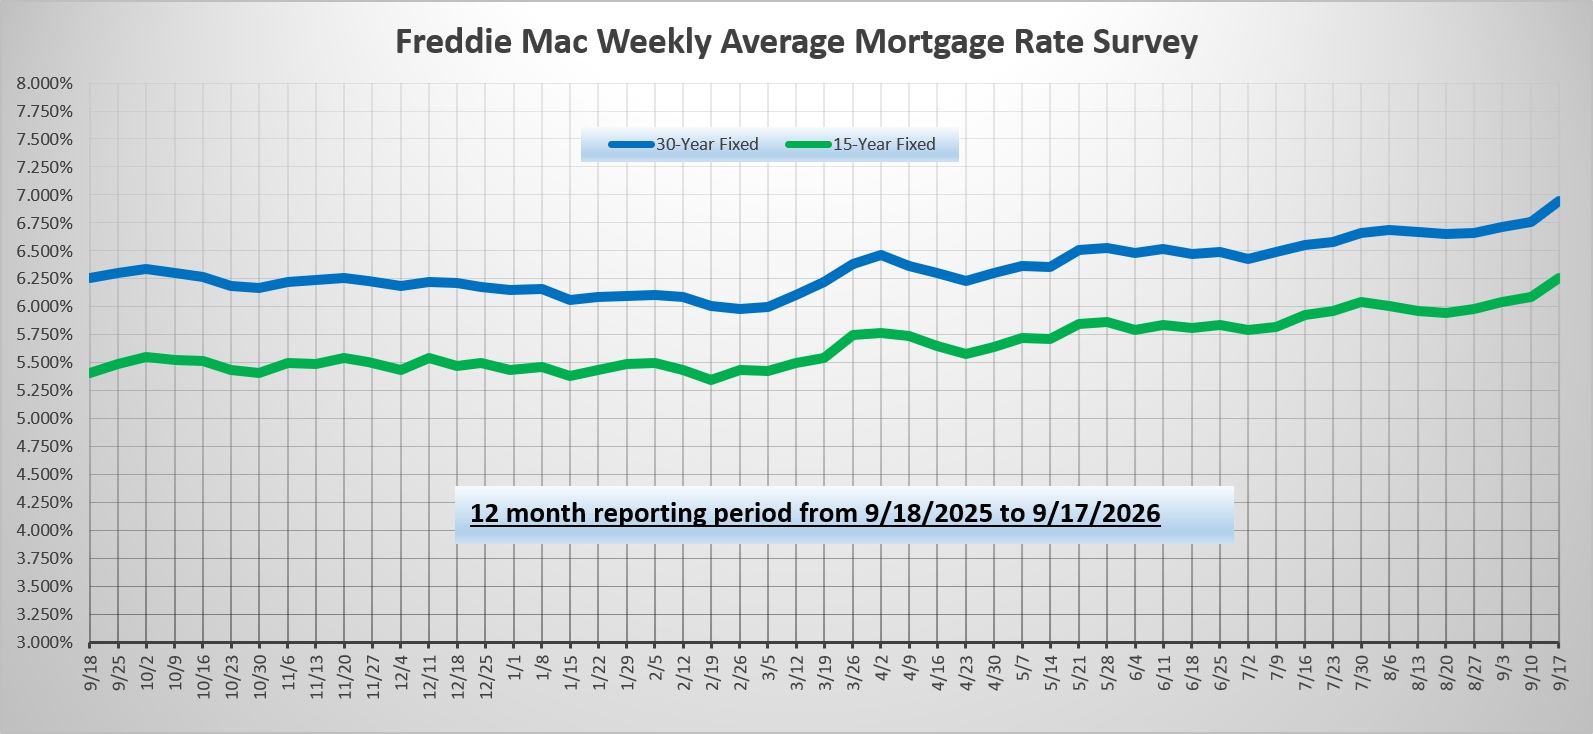
*** Please note that Freddie Mac publishes their weekly rate report on Wednesday mornings from data received Monday and Tuesday.
The graph above is intended to shown rate trends, and not “today’s current rate”. ***
Reviews From Our Past Clients
With every client, we promise to provide you with a comprehensive analysis of your mortgage needs, the best service possible, and the best rates we can find. We make it our mission to have every transaction close with our clients happy with the service we provided. Browse through the hundreds of reviews we’ve received from our clients posted on both Google and Zillow.com, and read what they thought of their experience using Hawaii Mortgage Company.
Google Link:
Hawaii Mortgage Company Review on Google.com
Zillow.com Link:
Hawaii Mortgage Company Reviews on Zillow.com
Our Rate Quote System is Available to You
Our automated rate quoting system is live. Now you can check rates and try different scenarios 24-hours a day. Remember, it’s just a computer. For non-standard rate quotes, such as construction, vacant land, and other specialty programs, you’ll still need to give a call.
Here’s the link: https://www.hawaiimortgage.net/todays-rates/

Do you think all lenders are the same?
There is a difference when you use Hawaii Mortgage Company for your financing. Here’s a short video telling you why:

Broker vs. Banker?
Click the link below to get a quick lesson on why working with a Mortgage Broker will benefit you on your next transaction.


