

Compliments of
 Alan Van Zee
President | NMLS #: 297154
Hawaii Mortgage Company, Inc.
Company NMLS #: 232582
Alan Van Zee is one of the top producing Mortgage Originators in the state, originating over $2,000,000,000 to date. He has written and published this weekly newsletter for the past 19 years. It is the most widely read mortgage, real estate, and finance publication in Hawaii.
Hawaii Mortgage Company, now in our 28th year of providing mortgages to the people of Hawaii, is proud to have a complaint-free history. We make sure our clients are happy!
News and Insight
For the Weekend of September 26th, 2026
Hawaii’s Most Read Mortgage, Real Estate, and Finance Publication for 18 Years
Volume 19 – Issue 5
Time to Use Your ARM’s
The mortgage headlines this week were all about rising rates and what to do. I’ve been providing mortgages here in Hawaii for 29 years. This isn’t my first experience with higher rates. The best advice I can give if you are shopping for a home right now or are contemplating a refinance is not to panic.
The one thing I’ve learned from watching mortgage rates all these years is that the factors that control the bond market, specifically the bond buyers, definitely have a heard mentality. Once the crowd gets an idea placed in their collective minds, everyone follows suit, until the next collective idea strikes. Right now, the collective thought is this: higher oil prices and additional government spending will create inflation. With inflation pressure, investors don’t want to buy bonds, unless their yield (rate offered to buy them) is high enough. What’s odd is that the last time oil prices surged a few years ago, the fear ran in the opposite direction – that consumers spending more to fill their tanks will cut back on other purchases which would result in a mini-recession. The point is - the crowd will go with what everyone else believes right now. Once the conflict with Iran is over, or when global investors believe it is over, bond yields and mortgage rates will decline.
But what does Joe & Jane Aloha do right now? They have 3 options:
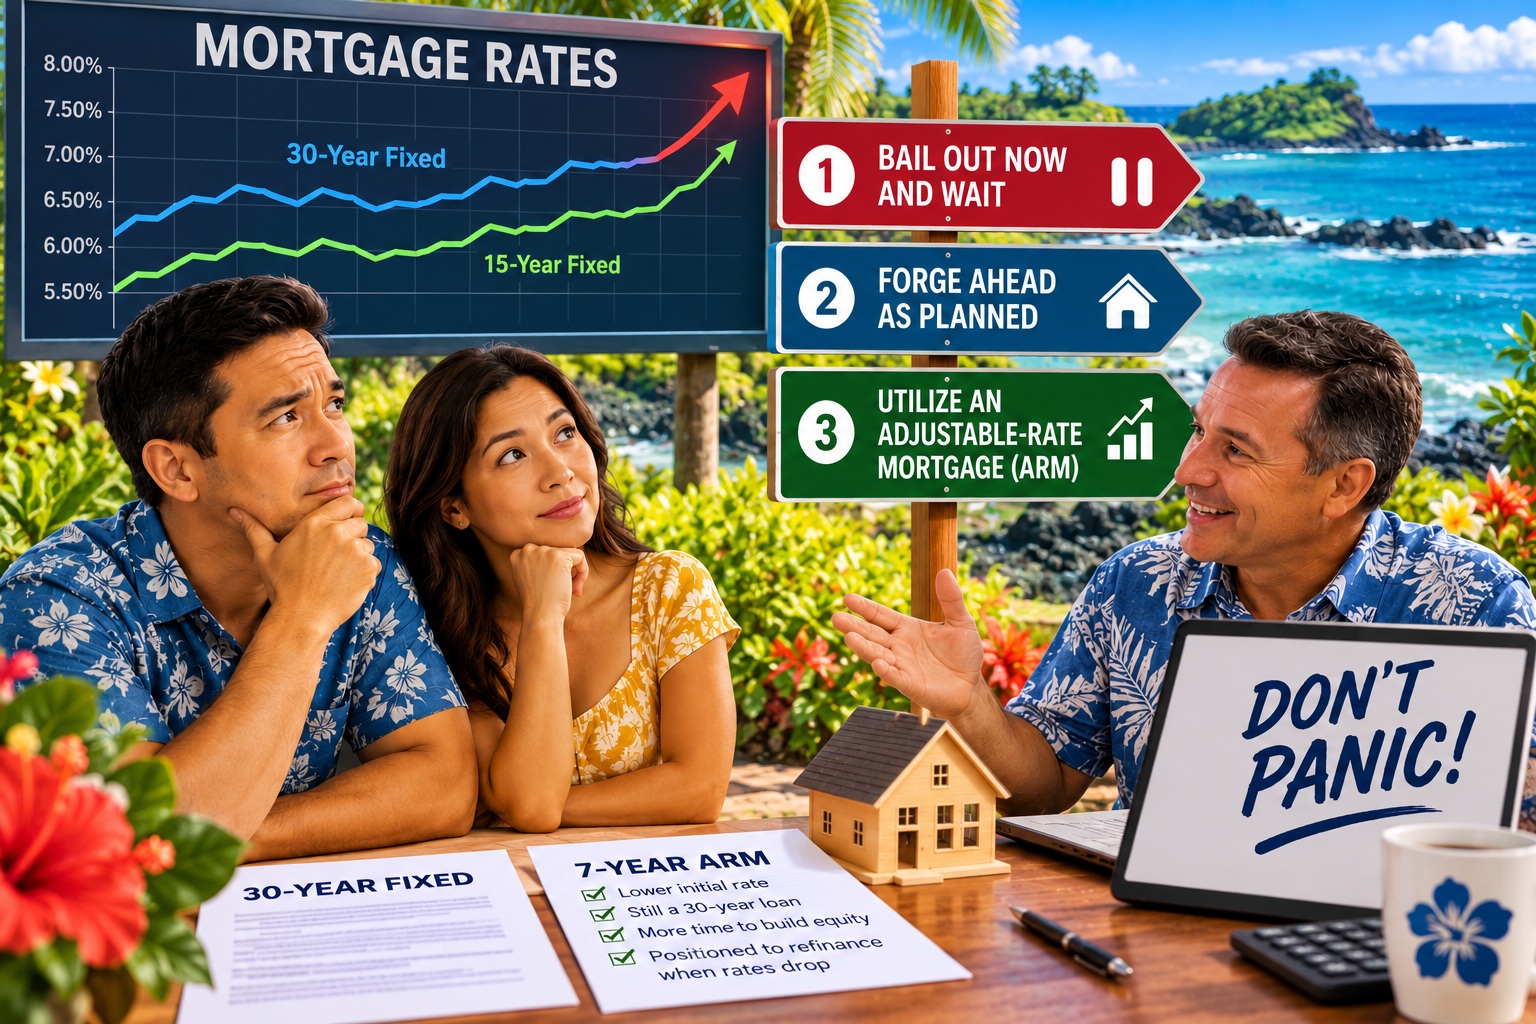
Option #1: Bail out Now and Wait
Yup, the easiest option, but not the smartest option is to call it quits for now to either buy a home pass on that refinance. With higher rates and fewer buyers, buyers are once again in the driver’s seat. Smart people will realize that it makes more sense to negotiate a lower sales price with a not-so-favorable interest rate, than have a better rate but a higher purchase price. After all, when rates come down you can always refinance. It’s impossible to get a seller to discount their home price in the future when there’s lots of buyers.
Option #2: Forge Ahead as Planned
What I mean by this is to proceed with your purchase or refinance with your original plan of utilizing a 30-year fixed rate mortgage. Better than option #1 but still has a flaw. Because mortgages have had a nearly two decades run of stable rates, everyone thinks that the 30-Year Fixed mortgage is the only way to finance a property. The mortgage product is the car that gets you there. There’s a lot of different cars to choose from. If you insist on the 30-Year Fixed as your loan of choice, negotiate with your seller to offer a credit that can be applied to get you a lower rate.
Option #3: Utilize an Adjustable-Rate Mortgage
The smart people will realize that sellers are getting nervous – not all, but a lot. For those that need to sell to move on with their lives, they will be motivated to offer a discount on the purchase price or be willing to offer a closing credit, or both! The smart play is to take advantage of the situation and also get the best mortgage rate possible right now utilizing an adjustable-rate mortgage. If you are unaware ARM’s as we call them are still 30-year loans – the only difference is the interest rate is fixed for a specific number of years (7 is the mort popular right now) instead of all 30 years. That 7-year window gives you more than enough time to gain equity and get ready to refinance when rates do drop sufficiently make a refinance worth doing. Because a lender doesn’t need to guarantee the rate for all 30 years, rates are lower than those offered for the 30-Year Fixed.
More on your offer strategy:
I want to share a call I had with a really smart real estate agent who happens to be one of the top agents in the state. The seller this agent was representing was having great success with open houses. Lots of traffic and positive comments. The issue they face is higher interest rates. That’s the major feedback they got as to why no offers were coming in. This agent called me to get answers to two very important questions:
- What is the maximum seller contribution towards a buyer’s closing costs?
- How much would it cost to buy points to drop the mortgage interest rate?
The sellers know the house is priced right, but they are motivated to sell. They have some money on the table to help a buyer get a below market interest rate. This smart agent had the great idea of presenting the home with discounted financing compliments of the seller. Not only does this separate this home from the competition, but it also removes a key complaint buyers gave. This is a great strategy for not only agents that read this newsletter to use with their listings, but for consumers that are reading this, use this tactic to get a better loan.
I know this expression sounds corny, because it is, but it is also true. You date the rate, but you marry the home. The mortgage rate you get today is not your forever rate. Most people refinance or sell, or in some way get rid of their current mortgage on average in 8 years. Find the home you like today. That’s what you’re marrying. Don’t let higher rates today discourage you from finding the home you want now.
And now the week’s economic news…….
Rates on the Rise
Despite a lack of major economic news, it was a rough week for mortgage markets. The upward trend seen in recent months continued, and mortgage rates climbed to their highest levels in over two years.
Long-term bond yields, including the yields that influence U.S. mortgage rates, have been moving higher around the world for several reasons. First, inflation remains elevated in many countries, and higher oil prices since the start of the conflict in the Middle East have added inflationary pressure. When investors expect inflation to remain higher, they typically want a larger return on their investments to protect their purchasing power. Second, investors are keeping a close eye on government spending. Governments around the world are running large deficits and need to issue more debt to fund them. With more bonds competing for money from investors, yields generally need to rise to attract buyers. Another factor is the huge amount of money being invested in artificial intelligence. Technology companies are spending heavily on building AI infrastructure, increasing their need for capital. That means they are also willing to offer higher returns on corporate bonds to attract investors. Put it all together, and there's a lot of demand for investor capital at the same time that the supply of bonds is increasing, pushing mortgage rates higher.
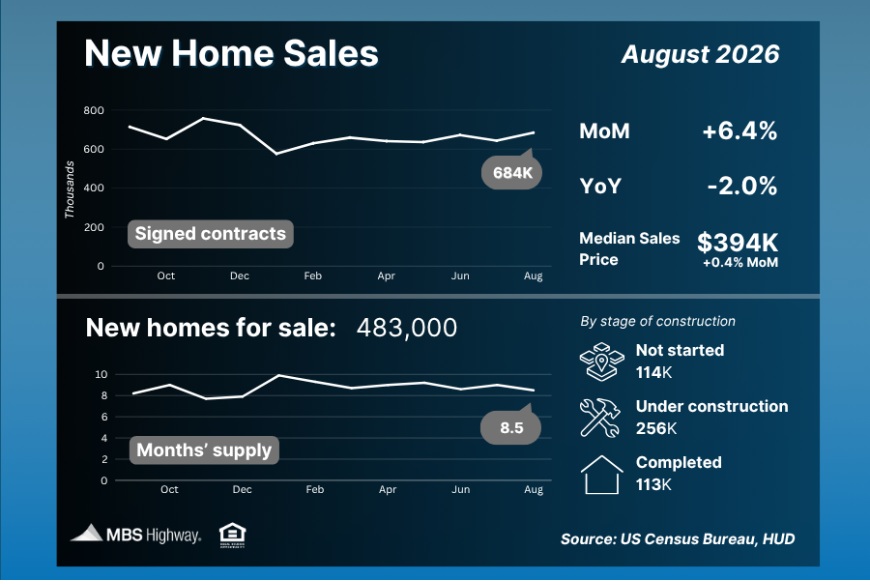
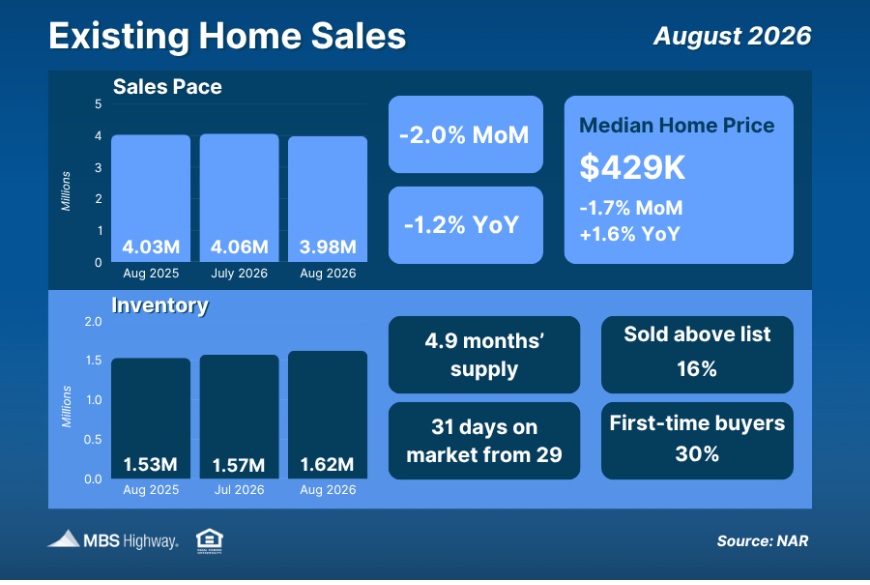 In housing news, sales of previously owned homes in August slipped 2% from July to the lowest level since June 2025. Inventory remains one of the biggest challenges for buyers, as there is only a 4.9-month supply of homes nationally. In another report, a survey of home builder sentiment on housing market conditions from the NAHB unexpectedly dropped to 32, the lowest level in a year, and has remained in negative territory below 50 for twenty-nine straight months.
 According to the Mortgage Bankers Association, higher mortgage rates in recent weeks have been negative for overall loan origination activity but have boosted demand for adjustable-rate loans that offer lower rates. Applications to refinance dropped 3% from last week and were a massive 62% lower than one year ago, at the lowest level since February 2025. Purchase applications fell 1% from the prior week and were down 11% from last year at this time. The adjustable-rate mortgage share of total applications rose to nearly 10%, the highest level in almost a year.
Bottom Line: Expect more volatility in mortgage rates as investors digest comments from Fed officials, upcoming economic reports, and changing oil prices tied to the conflict in the Middle East. Housing activity may be challenged if rates do not ease in the months ahead.
Next Week
Looking ahead, attention will remain fixed on the conflict in the Middle East and oil prices. Investors also will monitor comments from Fed officials about future monetary policy. For economic reports, Personal Income and the PCE price index, the inflation indicator favored by the Fed, will be released on Wednesday. The ISM national manufacturing sector index will come out on Thursday. The key Employment report will be released on Friday, and these figures on the number of jobs, the unemployment rate, and wage inflation are always closely watched.
Until next week….

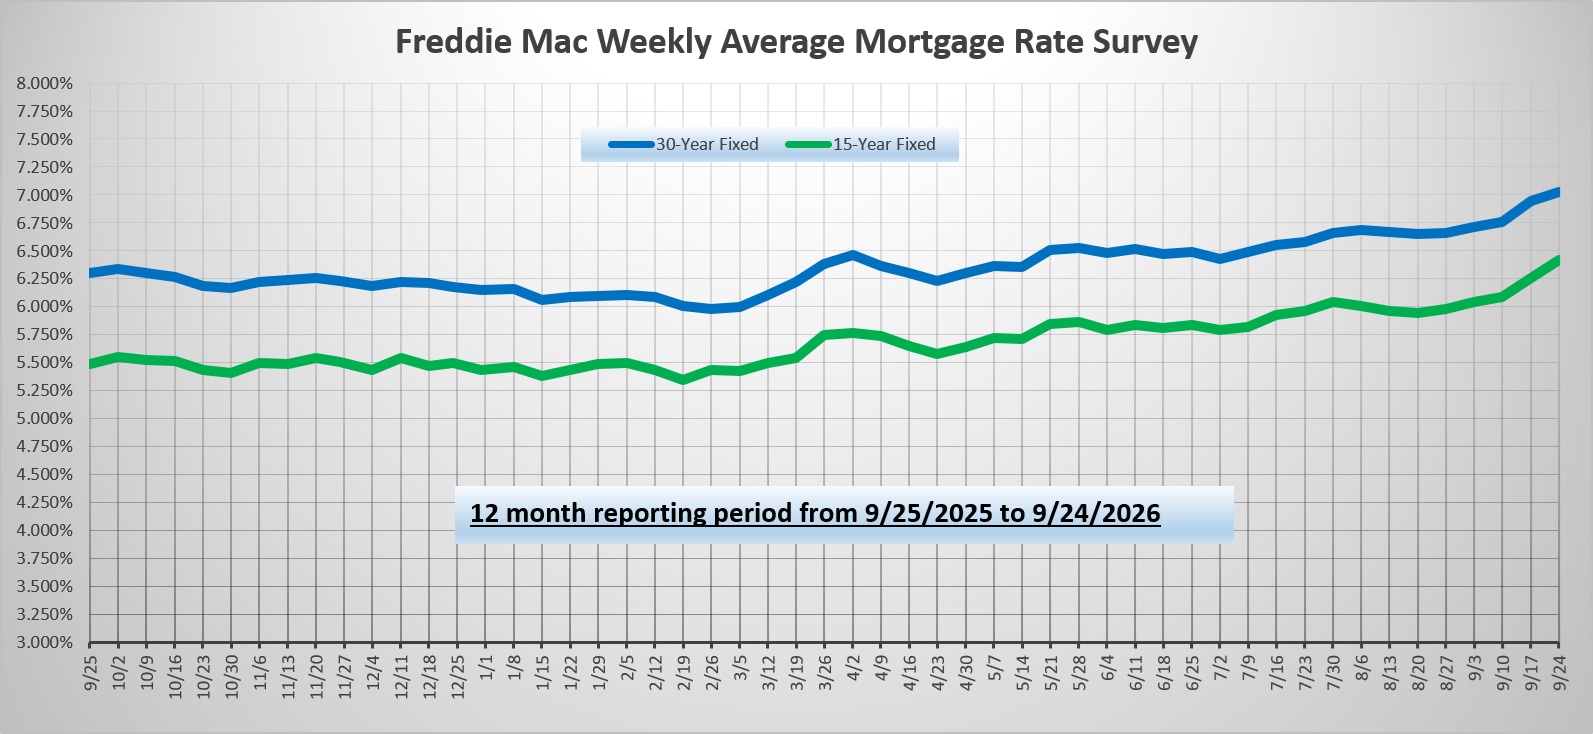
*** Please note that Freddie Mac publishes their weekly rate report on Wednesday mornings from data received Monday and Tuesday.
The graph above is intended to shown rate trends, and not “today’s current rate”. ***
Reviews From Our Past Clients
With every client, we promise to provide you with a comprehensive analysis of your mortgage needs, the best service possible, and the best rates we can find. We make it our mission to have every transaction close with our clients happy with the service we provided. Browse through the hundreds of reviews we’ve received from our clients posted on both Google and Zillow.com, and read what they thought of their experience using Hawaii Mortgage Company.
Google Link:
Hawaii Mortgage Company Review on Google.com
Zillow.com Link:
Hawaii Mortgage Company Reviews on Zillow.com
Our Rate Quote System is Available to You
Our automated rate quoting system is live. Now you can check rates and try different scenarios 24-hours a day. Remember, it’s just a computer. For non-standard rate quotes, such as construction, vacant land, and other specialty programs, you’ll still need to give a call.
Here’s the link: https://www.hawaiimortgage.net/todays-rates/

Do you think all lenders are the same?
There is a difference when you use Hawaii Mortgage Company for your financing. Here’s a short video telling you why:

Broker vs. Banker?
Click the link below to get a quick lesson on why working with a Mortgage Broker will benefit you on your next transaction.


