
Compliments of
 Alan Van Zee
President | NMLS #: 297154
Hawaii Mortgage Company, Inc.
Company NMLS #: 232582
Alan Van Zee is one of the top producing Mortgage Originators in the state, originating over $2,000,000,000 to date. He has written and published this weekly newsletter for the past 19 years. It is the most widely read mortgage, real estate, and finance publication in Hawaii.
Hawaii Mortgage Company, now in our 28th year of providing mortgages to the people of Hawaii, is proud to have a complaint-free history. We make sure our clients are happy!
News and Insight
For the Weekend of October 10th, 2026
Hawaii’s Most Read Mortgage, Real Estate, and Finance Publication for 18 Years
Volume 19 – Issue 7
When Did Good Become Not Good Enough?
If you're a sports fan, you probably know the feeling.
Remember when the San Francisco Giants won three World Series championships in five years? In 2010, 2012, and 2014, Giants fans had plenty to celebrate. For a while, it almost seemed like winning championships was becoming a regular occurrence. Or consider the Raiders. During their glory years in Oakland and Los Angeles, they won three Super Bowls and established themselves as one of professional football's most successful franchises. Their fans came to expect winning seasons and championship appearances.
Those were great times to be a fan. Today, neither franchise is enjoying that same level of success. But does that mean their fans should stop watching? Stop cheering? Stop enjoying the games until their teams become champions again? Of course not. We still enjoy following our favorite teams, even when they're not as good as they once were.
And that brings me to mortgage rates.
During 2020 and 2021, mortgage rates fell to levels most Americans had never experienced. According to Freddie Mac, the average 30-year fixed mortgage rate reached an all-time low of 2.65% in January 2021. For homebuyers and homeowners refinancing their mortgages, it was an extraordinary opportunity. Millions of Americans secured financing at rates that previous generations could only dream about.
But something interesting happened. After experiencing those exceptionally low rates, we began thinking of them as normal. And when rates started climbing again, anything above 5% suddenly seemed expensive. At 6%, people became uncomfortable. At 7%, some are wondering whether buying a home makes financial sense anymore. Now, with Freddie Mac reporting an average 30-year mortgage rate of 7.40% this week, the concern is understandable.
But are today's mortgage rates really that high? Or have our expectations been distorted by how unusually low rates became? Take a look at this chart below showing mortgage rates since 1971.
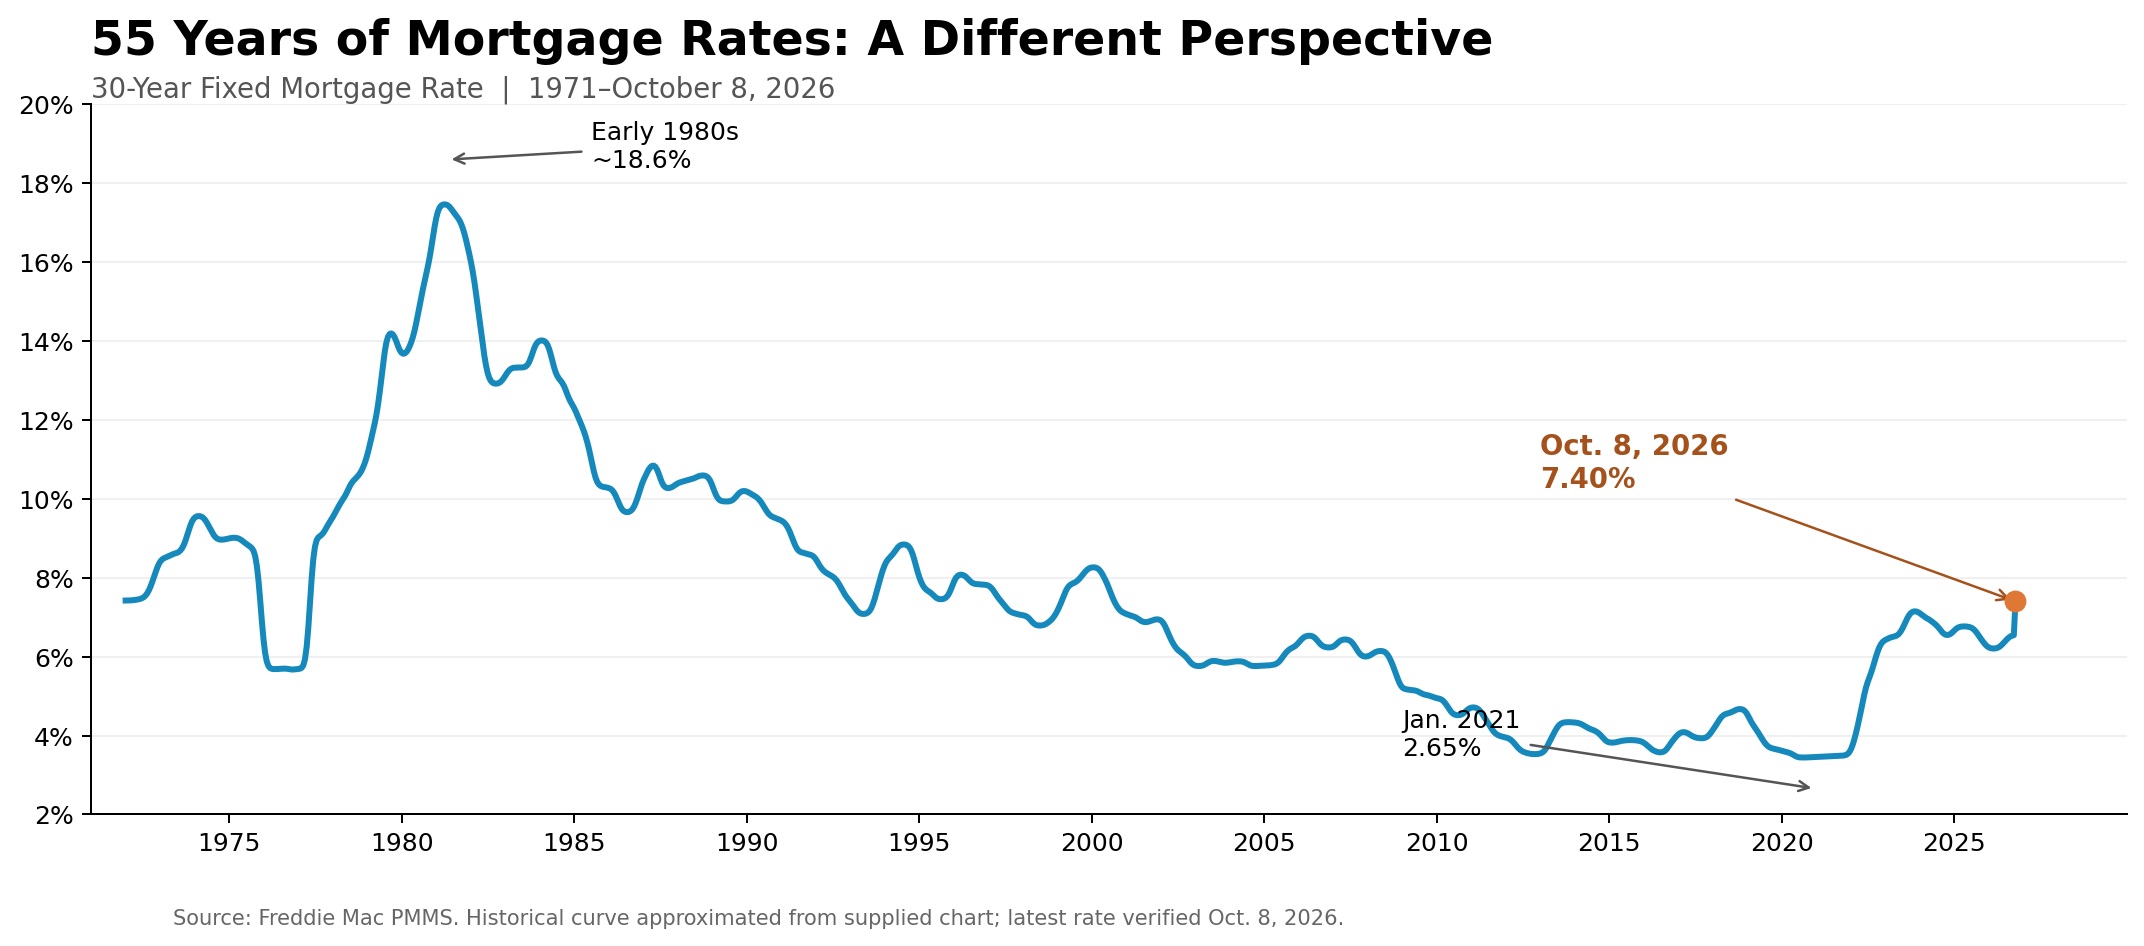
In the early 1980s, mortgage rates exceeded 18%. Throughout much of the 1990s, rates generally ranged between 7% and 10%. Even during the early 2000s, rates frequently approached or exceeded 7%. Over the past 55 years, the average 30-year fixed mortgage rate has been approximately 7.7%. That means today's rates, while certainly higher than we've experienced in recent years, are actually slightly below the long-term historical average. Think about that for a moment.
Maybe the problem isn't that today's mortgage rates are historically unreasonable. Maybe it's that we became accustomed to something historically extraordinary. Now, don't misunderstand me. I'm certainly not suggesting today's housing affordability challenges aren't real. Home prices have risen substantially, and financing those prices at 7% rather than 3% makes an enormous difference in monthly payments. That's something every prospective homebuyer needs to evaluate carefully.
But there's another consideration that sometimes gets overlooked. Life doesn't necessarily wait for ideal market conditions. People get married. Families grow. Children leave home. Careers change. People retire. Sometimes the house that was perfect ten years ago simply doesn't meet a family's needs anymore. Should someone put those decisions on hold indefinitely, hoping mortgage rates someday return to 3%? For some people, waiting may absolutely be the right decision. For others, it may mean postponing important opportunities while waiting for conditions that might not return anytime soon.
And here's something worth remembering. When mortgage rates eventually decline, homeowners may have opportunities to refinance their existing mortgages. There's no guarantee rates will fall, of course, but the financing available when someone purchases a home isn't necessarily the financing they'll have forever.
Which brings me back to the Giants and Raiders. Their fans remember those championship seasons fondly. They'd certainly love to experience them again. But they don't stop being fans simply because their teams aren't winning championships. They continue enjoying the game.
Perhaps we should look at mortgage rates with a similar perspective. Appreciate how wonderful those historically low rates were, recognize that today's circumstances are different, and make decisions based on what makes sense for our lives today. Because if we spend our lives waiting for another championship season, we might miss a lot of great games along the way.
And now the week’s economic news…….
Services Excel
Mortgage markets had another bumpy week as oil prices fluctuated, and investors digested the latest news from the Federal Reserve and the economy. Rates climbed to their highest levels in nearly three years early in the week but settled back down, ending the week close to where they started.
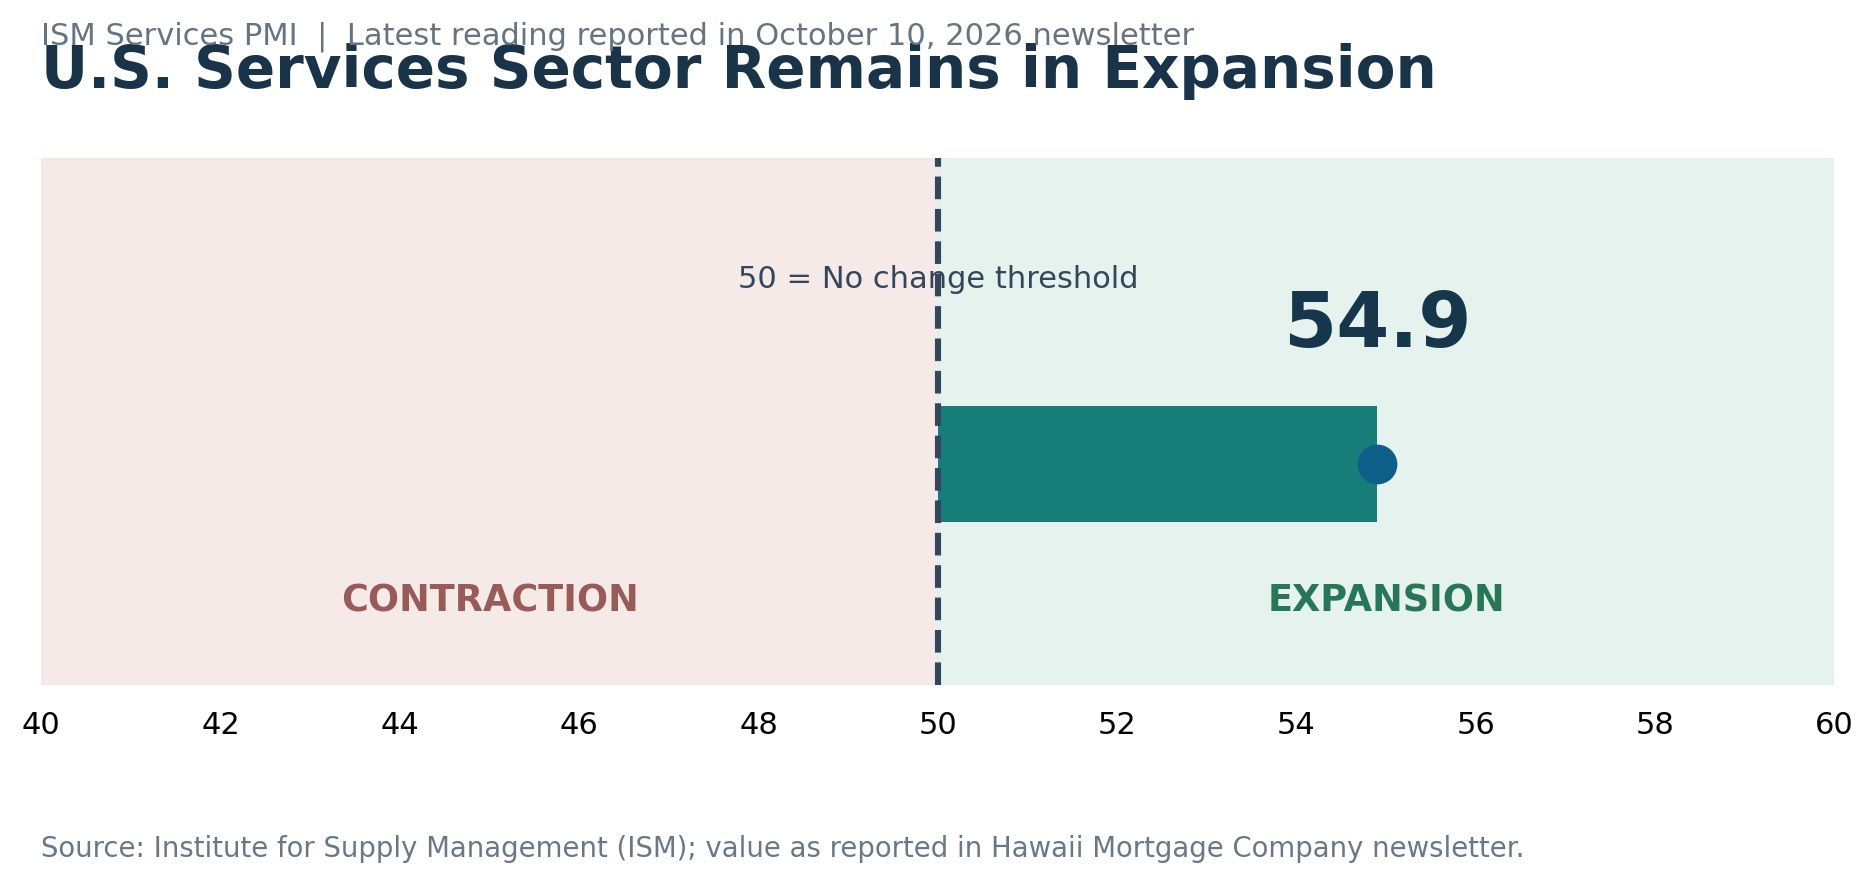 The most significant economic report released this week came from the Institute of Supply Management. The ISM national services sector index was 54.9, close to expectations. The sector remains comfortably in expansion territory above 50, suggesting businesses are still growing despite ongoing economic challenges.
We also got a closer look at the most recent Federal Reserve meeting on September 16 through the release of its meeting minutes. The minutes revealed that Fed officials have differing views on where inflation is headed and what that means for future interest rate decisions. Uncertainty around oil prices and tariffs is making the outlook even harder to predict. For now, the Fed is taking a wait-and-see approach, with future decisions likely to depend heavily on incoming economic data. Investors are increasingly expecting the next policy move to be a rate hike in December, although that could change as new information comes in.
According to the Mortgage Bankers Association, higher mortgage rates in recent weeks have been negative for overall loan origination activity but have boosted demand for adjustable-rate loans that offer lower rates. Applications to refinance dropped 8% from last week and were a massive 56% lower than one year ago, at the lowest level since February 2025. Purchase applications fell 2% from the prior week and were down 15% from last year at this time. The adjustable-rate mortgage share of total applications rose to over 10%, the highest level in about a year, up from levels around 3% in the early years of the pandemic.
Bottom Line: There's a lot for investors to keep an eye on right now, including persistent inflation, signs of slower economic growth, and ongoing global uncertainty. All of this could mean more volatility in the weeks ahead. Mortgage rates can change quickly as new economic reports, Fed comments, and global developments hit the headlines.
Next Week
Looking ahead, attention will remain fixed on the conflict in the Middle East and oil prices. For economic reports, Existing Home Sales will come out on Tuesday. The Consumer Price Index (CPI), a widely followed monthly inflation indicator that looks at the price changes for a broad range of goods and services, will be released on Wednesday. The Producer Price Index (PPI) and Retail Sales will come out on Thursday. Mortgage markets will be closed on Monday for Columbus Day.
Until next week….

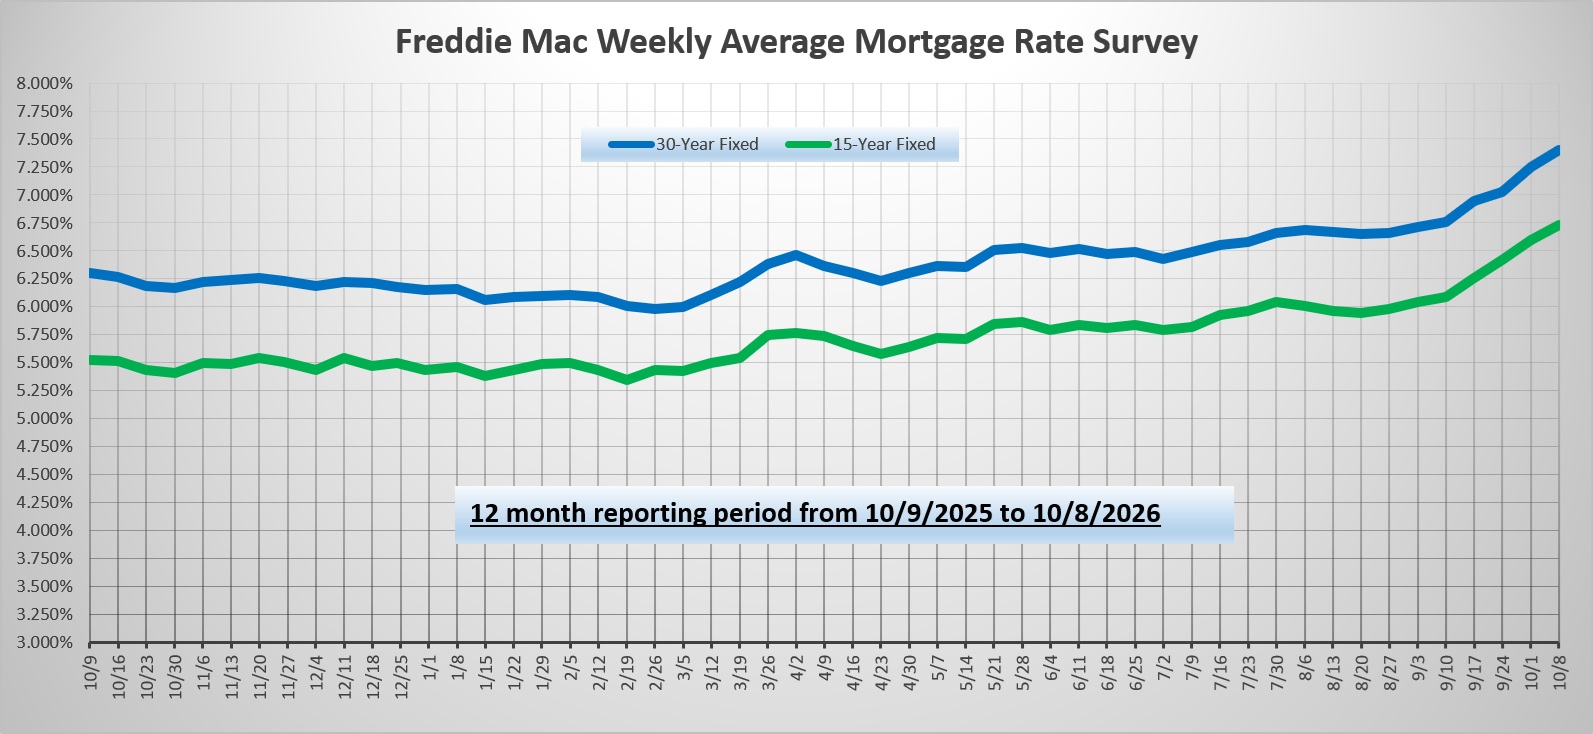
*** Please note that Freddie Mac publishes their weekly rate report on Wednesday mornings from data received Monday and Tuesday.
The graph above is intended to shown rate trends, and not “today’s current rate”. ***
Reviews From Our Past Clients
With every client, we promise to provide you with a comprehensive analysis of your mortgage needs, the best service possible, and the best rates we can find. We make it our mission to have every transaction close with our clients happy with the service we provided. Browse through the hundreds of reviews we’ve received from our clients posted on both Google and Zillow.com, and read what they thought of their experience using Hawaii Mortgage Company.
Google Link:
Hawaii Mortgage Company Review on Google.com
Zillow.com Link:
Hawaii Mortgage Company Reviews on Zillow.com
Our Rate Quote System is Available to You
Our automated rate quoting system is live. Now you can check rates and try different scenarios 24-hours a day. Remember, it’s just a computer. For non-standard rate quotes, such as construction, vacant land, and other specialty programs, you’ll still need to give a call.
Here’s the link: https://www.hawaiimortgage.net/todays-rates/

Do you think all lenders are the same?
There is a difference when you use Hawaii Mortgage Company for your financing. Here’s a short video telling you why:

Broker vs. Banker?
Click the link below to get a quick lesson on why working with a Mortgage Broker will benefit you on your next transaction.


