
Compliments of
 Alan Van Zee
President | NMLS #: 297154
Hawaii Mortgage Company, Inc.
Company NMLS #: 232582
Alan Van Zee is one of the top producing Mortgage Originators in the state, originating over $2,000,000,000 to date. He has written and published this weekly newsletter for the past 19 years. It is the most widely read mortgage, real estate, and finance publication in Hawaii.
Hawaii Mortgage Company, now in our 28th year of providing mortgages to the people of Hawaii, is proud to have a complaint-free history. We make sure our clients are happy!
News and Insight
For the Weekend of September 5th, 2026
Hawaii’s Most Read Mortgage, Real Estate, and Finance Publication for 18 Years
Volume 19 – Issue 2
How to Help Your Child Build Credit: What I Learned the Hard Way
Helping your child establish good credit before they truly need it can give them an important financial head start. I recently tried to do exactly that with my college-age son. My plan seemed simple: open a secured credit card in his name, teach him to use it responsibly, and let him begin establishing his own credit history.
The plan was good. The execution turned into a banking nightmare. Here's what happened—and what I would recommend parents consider before helping a young adult establish credit.
I’ve written recently about dropping my son off at college. One of the things I encourage all parents to do as part of helping set up their child for that next phase of their life is to start them on a path of financial education and success. This story is shared to help you educate yourself on issues that arose with me, and that you can hopefully avoid.
The best gift you can give your emerging adult headed off to school is to start their financial history with a credit card. Today, with the accepted use of debit ATM cards, most parents think that’s sufficient. These types of cards, while they act like a credit card at merchants, doesn’t report credit history – which is the vital goal, not ease of spending.
I was aware that without any credit history and no income, my son would not qualify for a credit card on his own. Yes, I could add him to one of mine, but I wanted him to build and earn his own good credit. One way to accomplish that is by utilizing a collateralized credit card. These are regular credit cards just like any other, except your credit limit is tied to an equal amount you put into a savings account at that financial institution. You still need to pay your bill each month. You don’t use that money in the savings account for that. Collateralized credit cards are not a pre-paid credit cards – those are completely different.
You can search online for the best offers for these types of cards, which is what I did. One of the highly rated cards was through Bank of America. I sat with my son in front of the computer and coached him to complete the online application process. Within minutes he was approved. I had to take the next step of funding his account. I used an electronic transfer of $500 from my account into a savings account held by Bank of America.
That was the only smooth part of the transaction.
My son tried to access the new online account set up during the application process to specify things like electronic statements versus mailed paper statements and to set up auto-pay. Unfortunately, he could get into his account. We called the customer support number listed and waited on hold for 30 minutes. When we finally spoke with a human, we were told that since the account was opened online, my son would need to physically go into any Bank of America branch to verify his identity. They said this is how they minimize fraud – something I can agree is a good thing. Without a branch here in Hawaii, we then added stopping by a Bank of America branch just one more task on our way to college move-in day.
His card arrived in the mail prior to us leaving for the mainland. Up on the mainland we went into a branch to verify he is the person that applied for the card. The odd thing about this procedure is that the local bank representative’s only function is to call an internal BoA phone number and verify that they checked my son’s identification in person. My son still needed to talk to the phone representative while in the presence of the local bank employee. We waited about 15 minutes to see the local customer service person, and we were only on hold for about 5 minutes. My son went through the verification process with the local representative and the customer service agent on the phone. We left the bank thinking everything was now set up.
In reality, that visit to the branch didn’t resolve anything. After our sad goodbye at college move-in and I was already back home in Hawaii, my son discovered that the credit card still wasn’t authorized for use, and he still lacked the ability to log into his account. He called BoA’s customer service number and was on hold for almost an hour! He was told that “something went wrong” and that he would need to go back into a branch to get it resolved.
Earlier this week my son got a friend from school with a car to drive him to a local BoA branch. He waited over an hour before a customer service representative was free to help him. They then waited together for almost an hour on hold waiting for the internal BoA people to answer. No one ever did. They waited on hold so long that the local branch had already closed for the day. The customer serviced rep had to go home to her kids, so she set an appointment for my sone to come back the next day.
Branch excursion #3 started off with the rep seeing my son without a wait. But it took almost an hour for anyone from BoA’s customer support center to get on the phone. When that person reviewed everything and said they couldn’t fix whatever was wrong with the account, the local rep asked for a manager. The call was simply put back in cue and no manager ever answered.
The local bank branch manager finally got involved. Unfortunately, there’s nothing she could do. Everything at BoA is tied to their call center. The branch employees completely understood that at this point my son would just want to cancel the card and move onto to another bank. Ironically, the only way he can do that is by calling customer service and waiting on hold for god knows how long. But the branch manager did warn my son that since he was just issued the card, if he tried to cancel it right away it could negatively impact his credit!
This saga has not only taught my son a lesson on just how bad corporate American has become, but gave him a taste of the frustration each of us “adults” has had to contend with in trying to deal with everything from an Amazon return to a fraudulent charge on a credit card.
When this issue gets resolved, I’ll be sure to give you all an update. In the meantime, it took me all of 5 minutes to go online and make my son an authorized user of one of my credit cards. In doing the research, he’ll instantly obtain a credit history on that card going all the way back to when the account was first opened. That’s how the system works. Ironically, if someone in the future were to look closely at my son’s credit profile, they’ll notice that he’s had a credit card longer than he’s been alive. I’m sure that will raise some red flags too.
If you asked me 2 months ago what is the best process to get your child established credit, I would have suggested a collateralized credit card. I still think it is the best route – so long as it is not from Bank of America. But if you want to make it clean and easy, make your child an authorized user on one of your cards. You can always cancel the authorization at any time.
This is my plan for my son going forward. I’m adding him to a couple of my credit cards for the next year. In 12 months, he’ll have sufficient credit history to apply for his own card(s). At that point I’ll remove him as an authorized user on my cards.
And now the week’s economic news…….
Job Gains Surge
Headlines surrounding the conflict in the Middle East continued to create some ups and downs in mortgage markets this week. At the same time, a surprisingly strong jobs report had less impact on rates than you might expect. By the end of the week, mortgage rates were slightly higher.
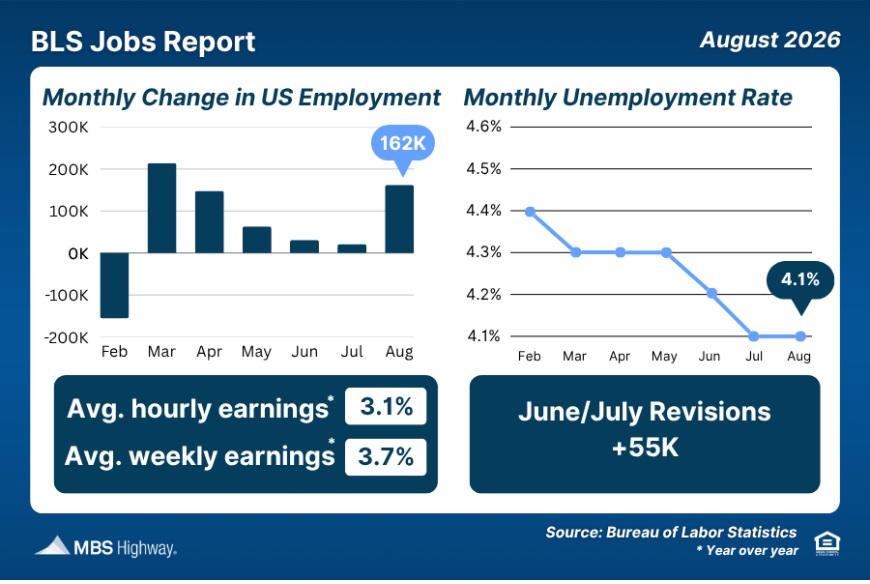 In August, the U.S. economy gained a massive 162,000 jobs, the most since March, surprising economists who had expected employers to add just 55,000 jobs. On top of that, payroll numbers for the previous two months were revised higher by a combined 55,000 jobs. The largest gains were seen in restaurants/bars, education, and manufacturing.
Despite the strong headline number, some of the other details were more in line with expectations. Average hourly earnings rose 0.3% for the month, bringing annual wage growth to 3.1%. That's down slightly from 3.2% the month before and marks the slowest annual increase since May 2021. The unemployment rate held steady at 4.1%, while the participation rate (the percentage of working-age people in the labor force) improved. After hitting its lowest level since March 2021 last month, participation has picked up as significantly more people have entered the workforce.
We also received two closely watched reports on business activity from the Institute for Supply Management (ISM). The services sector unexpectedly jumped to 55.4, while manufacturing dropped a bit to 54.6 from its strongest reading since May 2022 last month. Both sectors remain comfortably in expansion territory above 50, suggesting businesses are still growing despite economic headwinds. Shifting consumer preferences and higher tariffs on imported goods have helped domestic manufacturers narrow the performance gap with service firms over the last few years.
Bottom Line: For now, investors are balancing several competing forces: slowing economic growth, persistent inflation, and continued global uncertainty. Inflation has come down significantly from its peak, but it's still well above the Federal Reserve's target. That means the Fed is likely to remain cautious about its next moves. For mortgage rates, that could mean more volatility in the weeks ahead. Daily movements will continue to depend on incoming economic data, comments from the Federal Reserve, and developments around the world.
Next Week
Looking ahead, attention will remain fixed on the conflict in the Middle East. Investors also will monitor comments from U.S. Fed officials about future monetary policy. The next European Central Bank meeting will take place on Thursday. For economic data, Existing Home Sales and the Producer Price Index (PPI) will come out on Thursday. The Consumer Price Index (CPI), a widely followed monthly inflation indicator that looks at the price changes for a broad range of goods and services, will be released on Friday. Mortgage markets will be closed on Monday for Labor Day.
Until next week….

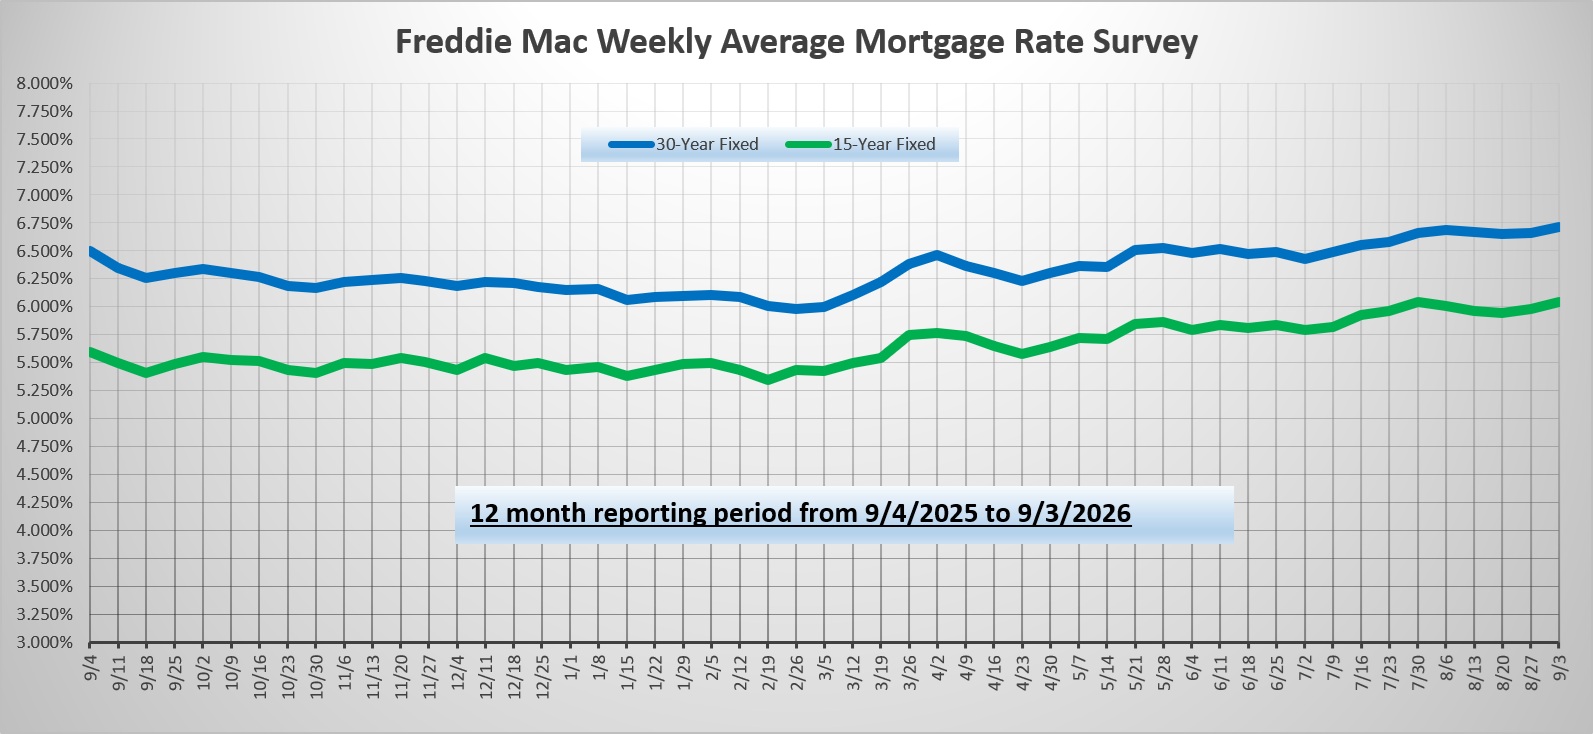
*** Please note that Freddie Mac publishes their weekly rate report on Wednesday mornings from data received Monday and Tuesday.
The graph above is intended to shown rate trends, and not “today’s current rate”. ***
Reviews From Our Past Clients
With every client, we promise to provide you with a comprehensive analysis of your mortgage needs, the best service possible, and the best rates we can find. We make it our mission to have every transaction close with our clients happy with the service we provided. Browse through the hundreds of reviews we’ve received from our clients posted on both Google and Zillow.com, and read what they thought of their experience using Hawaii Mortgage Company.
Google Link:
Hawaii Mortgage Company Review on Google.com
Zillow.com Link:
Hawaii Mortgage Company Reviews on Zillow.com
Our Rate Quote System is Available to You
Our automated rate quoting system is live. Now you can check rates and try different scenarios 24-hours a day. Remember, it’s just a computer. For non-standard rate quotes, such as construction, vacant land, and other specialty programs, you’ll still need to give a call.
Here’s the link: https://www.hawaiimortgage.net/todays-rates/

Do you think all lenders are the same?
There is a difference when you use Hawaii Mortgage Company for your financing. Here’s a short video telling you why:

Broker vs. Banker?
Click the link below to get a quick lesson on why working with a Mortgage Broker will benefit you on your next transaction.


